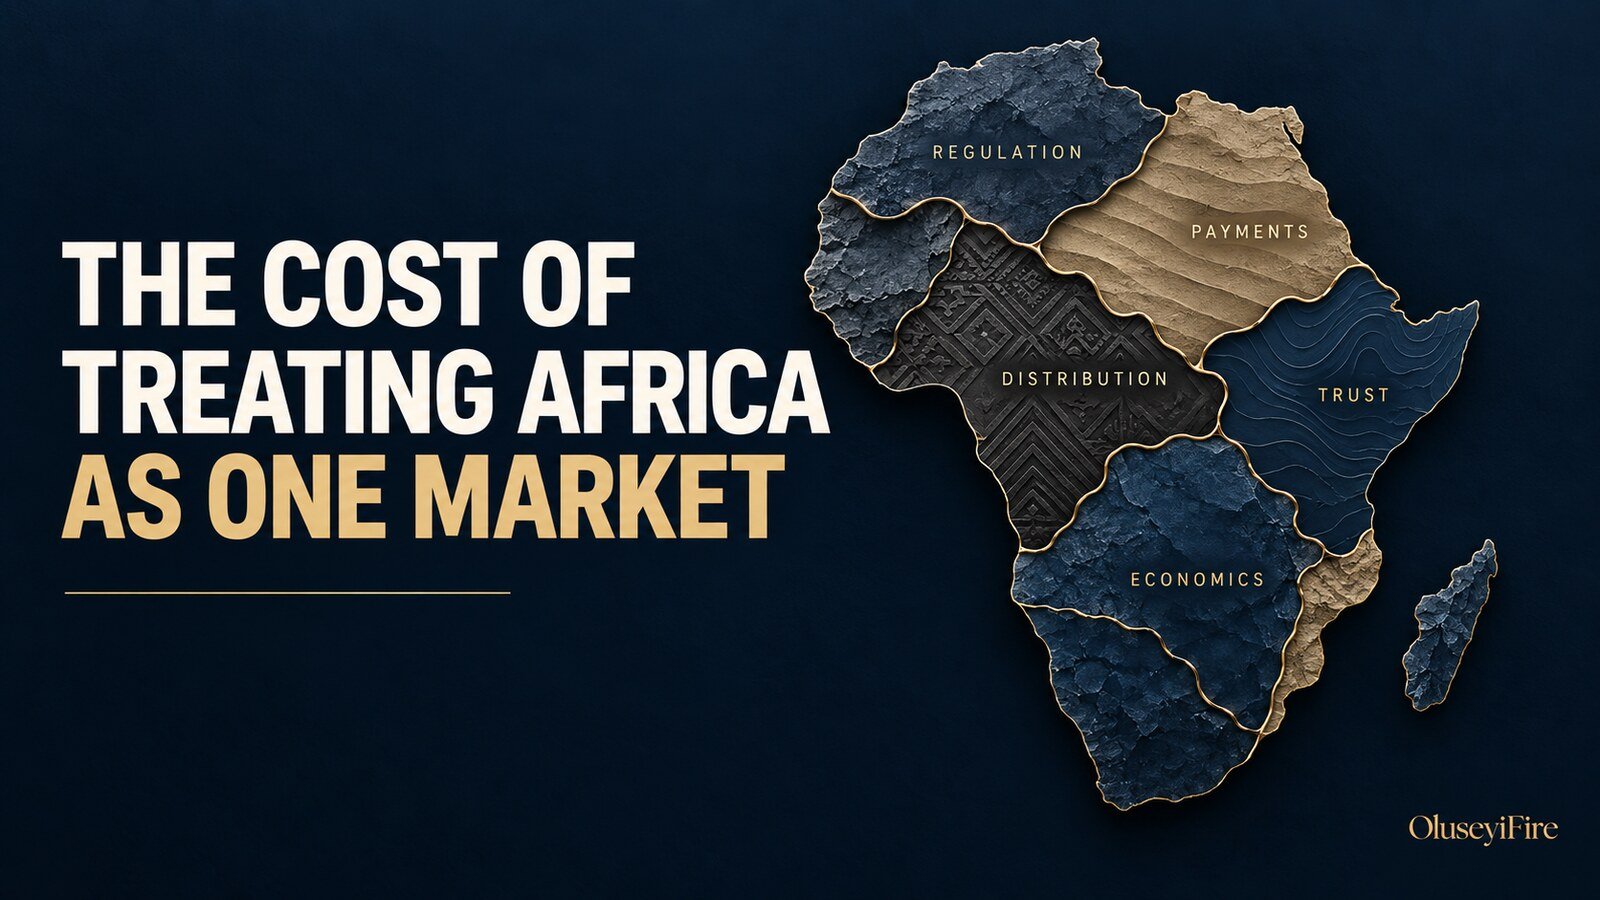
Africa is a useful portfolio label. It is a poor operating segment. African market fragmentation means that the commercial conditions determining whether a digital product succeeds can change at every border—and sometimes within one country.
A strategy that groups Nigeria, Kenya, Ghana and South Africa into one line on a regional plan may look efficient. It becomes expensive when the business begins acquiring customers, processing deposits, managing partners and meeting local regulatory obligations.
The problem is not that every market needs an entirely separate company. The problem is assuming that a shared technology platform creates a shared commercial reality.
It does not.
The interface may be reusable. The brand may be reusable. Some risk controls, data infrastructure and reporting standards should be reusable. But regulation, payment behaviour, trust, distribution and customer economics still have to be resolved locally.
That distinction changes how an operator should evaluate expansion. Market entry should not begin with the question, “How large is Africa?” It should begin with a more disciplined question: “In which specific market can our product, acquisition model and operating structure produce sustainable value?”
African market fragmentation changes the profit equation
Regional market sizing often combines populations, smartphone adoption and category growth into an attractive top-line opportunity. Those numbers can be useful for screening. They are not enough for an investment decision.
The real profit equation sits lower in the funnel:
- Can a customer complete registration on the device and connection they actually use?
- Can the business verify that customer without creating excessive abandonment?
- Can the customer deposit through a method they trust?
- Does the payment succeed consistently?
- Can the operator serve that customer legally and market to them compliantly?
- Can acquisition partners be measured and paid without losing control of traffic quality?
- Does retained customer value justify the cost of local operations?
Each answer is market-specific. A business can have high demand and still have weak economics because the operating conditions interrupt conversion between intent and revenue.
This is why African market fragmentation is not merely a localisation issue. It changes capital allocation. It determines where to enter, how quickly to scale, which functions can remain central and where local capability is essential.
Regulation changes the addressable market
Regulation is the clearest reason to reject a continent-wide operating assumption.
Nigeria alone demonstrates the problem. In November 2024, the Supreme Court held that lotteries and gaming are residual matters reserved for state governments. PwC’s analysis of the judgment notes that the National Lottery Act became inapplicable across the 36 states, while the National Assembly retained jurisdiction for the Federal Capital Territory. It also identifies potential duplicate licensing costs, different state requirements and uncertainty for online businesses serving customers across state boundaries.
That is not a small compliance adjustment. It changes how an operator defines coverage, sequences expansion, contracts with partners and calculates the cost of serving a customer.
South Africa presents a different structure. The National Gambling Board compiles audited national statistics from nine provincial licensing authorities. Its FY2024/25 report recorded total gross gambling revenue of approximately R74.5 billion, with material differences across provinces and gambling modes. A national total therefore sits on top of provincial regulatory and commercial realities rather than replacing them.
The lesson is broader than either country. A licence, product approval or advertising rule in one jurisdiction does not establish the operating position elsewhere. Before customer acquisition begins, the business needs a market-level legal and compliance view covering:
- the relevant regulator and licence scope;
- permitted products and channels;
- advertising and promotional restrictions;
- customer verification obligations;
- tax, levy and reporting requirements;
- affiliate and creator responsibilities;
- geographic restrictions and enforcement risk.
An “Africa launch” without that matrix is not a launch plan. It is a collection of unresolved liabilities.
Payment access is not payment performance
Digital payment adoption is often used as proof that a market is ready. The reality is more demanding.
The World Bank’s Global Findex describes substantial growth in financial inclusion across Sub-Saharan Africa, driven in part by mobile money. GSMA’s 2026 report also shows the economic weight of mobile technology across the continent. Yet GSMA reports that 63% of Africa’s population is covered by mobile broadband but remains offline, pointing to affordability, digital skills and social barriers.
These regional findings are useful because they reveal both progress and unevenness. They do not tell an operator which deposit method should lead in a particular market, what failure rate is commercially acceptable or how quickly customers recover from a failed transaction.
A payment method can be technically available and still perform badly. Customers may face unfamiliar steps, delays, limits, fees or inconsistent confirmation. A deposit flow designed around cards may struggle where customers prefer bank transfers or mobile money. A mobile-money-led journey can also fail if the integration, reconciliation or customer communication is poor.
The correct unit of analysis is not the number of payment logos on the cashier page. It is the completed deposit.
This article intentionally stays at the strategic level. The relationship between deposit success and conversion deserves separate treatment. The important point here is that payment behaviour cannot be inherited from a regional assumption. It must be measured inside each market.
Trust has local causes
Trust is often discussed as if it were a brand-awareness problem. In digital products, trust is more practical.
Customers want to know whether the product works, whether their money is safe, whether withdrawals arrive and whether support responds when something goes wrong. The sources of reassurance vary. In one market, an established local payment method may reduce anxiety. In another, a known affiliate, retail presence, community administrator or visible customer-service channel may matter more.
The same creative campaign can therefore produce different results even when reach and click-through rate look similar. The difference may be what customers believe will happen after the click.
My experience in Nigeria reinforced this point. Affiliate traffic could not be judged by registrations alone. Deposits, repeat activity, net gaming revenue and deal profitability had to be connected before the commercial value of a partner became clear. That is a Nigerian operating observation. It should not be presented as evidence that every African market behaves the same way.
The principle that travels is the need to identify the local trust mechanism. The mechanism itself must be discovered rather than assumed.
Distribution structures differ by market
A channel name does not describe the same capability everywhere.
“Affiliate” can refer to a search publisher, a tipster, a creator, a community owner, a retail introducer or a media business with several acquisition routes. Their audience relationships, compliance risks and measurement quality differ significantly.
The dominant route to discovery can also vary by category and market. Search may capture existing intent. Social creators may shape preference. Closed messaging communities may distribute offers through repeated personal contact. Retail and agent relationships can connect digital products to customers who still move between cash and electronic payments.
This has two consequences.
First, a partner programme needs local segmentation. Applying one commission structure and one approval process to every partner creates weak incentives and poor controls.
Second, channel performance should be compared using downstream value, not just reach or registrations. A smaller partner with trusted access to the right customer group may produce better economics than a larger source of loosely qualified traffic.
The business should preserve common standards for verification, tracking, compliance and payment approval. Partner selection and commercial terms, however, need to reflect how distribution actually works in the market.
Product design carries commercial assumptions
Product teams often treat market variation as a content or translation task. The deeper differences sit in the operating assumptions built into the customer journey.
Registration length, identity checks, default payment methods, data consumption, page weight, support access and promotional mechanics all influence conversion. Even when two markets share a language, they may not share the same device mix, payment behaviour, sporting preferences or tolerance for friction.
The product should therefore have a shared core and configurable local layers.
The shared core can include account architecture, risk rules, event tracking, data definitions and central reporting. Local layers can control payment priority, verification steps, permitted promotions, content emphasis, support routes and market-specific compliance messages.
This is more disciplined than either extreme. A single rigid product ignores market conditions. Building an entirely separate product for every country creates unnecessary cost and inconsistency.
The objective is controlled variation: common infrastructure where standardisation creates value, local configuration where differences affect conversion, compliance or trust.
Regional dashboards can hide local failure
Aggregation is useful for management. It is dangerous when it conceals causality.
An Africa-wide dashboard may show acceptable acquisition cost, deposit value or retention. One strong market can mask another where customers fail during verification, deposits decline or promotional costs exceed retained value.
The opposite can also happen. A newly launched market may look weak because early operating costs are high, even though its customer economics are improving. Combining it with mature markets can obscure the progress needed to make the right investment decision.
Regional reporting should therefore roll up from market-level profit and loss views. At minimum, each market needs its own funnel and economics:
- visits and registrations;
- verification completion;
- first-time depositors;
- deposit attempts and successful deposits;
- repeat deposits and retention;
- gross and net gaming revenue;
- promotional cost;
- partner cost;
- payment and operational cost;
- contribution after variable acquisition costs.
Shared definitions matter. Local interpretation matters just as much. If a registration, active customer or retained customer is defined differently across markets, the regional total becomes unreliable.
One-market thinking creates organisational cost
Fragmentation does not affect only marketing and product decisions. It changes the organisation required to operate responsibly.
A central team usually prefers one campaign calendar, one partner policy, one payment configuration and one reporting rhythm. Standardisation reduces cost when the underlying conditions are genuinely similar. When they are not, the apparent efficiency moves work elsewhere.
Customer support inherits questions caused by unsuitable payment journeys. Compliance teams investigate promotions that were approved without enough local context. Finance teams reconcile providers and partner arrangements that do not follow the same commercial logic. Product teams interrupt planned development to repair market-specific problems that should have been identified before launch.
These costs are easy to underestimate because they sit across several departments. No single team sees the complete total.
The same problem affects decision speed. If every market adjustment requires central approval, local teams cannot respond quickly to payment failures, regulatory notices or changes in partner quality. If local teams are given complete freedom, the business can lose control of risk, data definitions and financial commitments.
The answer is explicit decision ownership.
Central teams should normally own the controls that protect the whole business: financial approval limits, risk standards, data definitions, brand principles, platform security and core compliance governance.
Market teams should have defined authority over decisions that depend on current local evidence: channel emphasis, payment ordering, customer communication, partner prioritisation and escalation of regulatory issues.
This division should be documented before scale. Otherwise, the organisation discovers it during a crisis, when the cost of ambiguity is highest.
A practical market assessment framework
A market should be assessed across connected commercial dimensions rather than ranked by population alone.
Regulatory viability
Identify the licences, product permissions, taxes, reporting obligations and marketing restrictions that apply. Estimate both the direct compliance cost and the effect of restrictions on acquisition and product design. A market can be legally accessible but commercially unattractive once these requirements are included.
Payment readiness
Confirm which payment routes customers use, which providers can support them and how settlement and reconciliation work. Test the full deposit and withdrawal journey. Provider availability is not proof of customer readiness or reliable performance.
Trust and customer protection
Determine what gives customers confidence and what causes hesitation. Review withdrawal expectations, support access, responsible-gambling requirements, complaints handling and the credibility of prospective partners. Trust should be treated as an operating requirement, not a creative theme.
Distribution access
Map the partners and channels that can reach relevant customers. Verify ownership, audience quality, compliance history and measurement capability. A long contact list does not establish usable distribution.
Product fit
Test the registration journey, verification, payment order, page performance, content priorities and customer-service routes under real local conditions. Record where local configuration is enough and where the shared product requires structural work.
Unit economics
Build a market-level model from qualified traffic through contribution. Include partner cost, promotions, payment cost, customer support, compliance and the local operating capacity required. Use ranges when evidence is incomplete rather than presenting a single optimistic forecast.
Execution capacity
Assess whether the organisation has the people, decision rights and supplier relationships to operate the market after launch. Entry should not be approved merely because acquisition can begin. The business must be able to support customers, manage partners, monitor risk and produce reliable reporting.
These dimensions should not be collapsed into a decorative score. The purpose is to expose the specific assumptions that could prevent sustainable performance. A market with strong demand but unresolved licensing should remain blocked. A market with compliant access but weak payment performance should remain in testing. A market should receive more capital only as evidence improves.
Market entry should be staged
The assessment becomes more useful when it controls investment through clear stages.
The first stage is evidence gathering. The business verifies regulation, payment routes, customer needs, partner availability and likely operating cost without committing a full acquisition budget.
The second stage is controlled validation. A limited launch tests the customer journey and partner quality with explicit spending limits. The objective is not impressive registration volume. It is evidence that customers can register, fund, receive support and return at economics the business can sustain.
The third stage is measured expansion. More budget follows only when payment performance, retained value and operational readiness meet agreed thresholds.
The final stage is repeatable scale. Processes, reporting and local decision rights should be stable enough that growth does not create uncontrolled compliance, support or reconciliation work.
This staged approach also improves exit decisions. A market can be paused because a specific requirement remains unresolved rather than because a regional total feels disappointing. Capital can then move to a market with stronger evidence.
A stronger structure for multi-market growth
Treating Africa as a portfolio of markets does not require slow, bureaucratic expansion. It requires clear gates.
1. Build a market thesis before a launch budget
State why the product should win in that country. Identify the customer, the unmet need, the expected trust mechanism, the payment route and the distribution advantage. If the thesis is only population growth and category demand, it is incomplete.
2. Separate facts from assumptions
Record what has been verified through regulation, partner diligence, payment testing, product data and customer research. Keep assumptions visible. Do not let a regional presentation turn uncertain inputs into confident forecasts.
3. Define entry gates
Before scaling acquisition, require minimum evidence for licensing, payment performance, verification completion, support readiness and measurement. A market should earn more capital by meeting operating thresholds.
4. Keep one shared measurement standard
Use consistent definitions for acquisition cost, first-time depositors, retained customers, revenue and contribution. This allows comparison without pretending the markets are identical.
5. Give local teams real decision rights
Local insight is wasted if every change waits for a distant central team. Define which decisions can be made locally and which controls must remain central. Payment ordering, channel mix and customer communication often need faster local adjustment than core risk or financial policy.
6. Scale by evidence, not adjacency
A neighbouring country is not automatically the next logical market. Regulatory fit, payment readiness, distribution access and expected customer value should determine sequence. Geographic proximity is only one input.
The cost of one-market thinking
The cost of treating Africa as one market rarely appears as a single line in the budget. It accumulates across failed deposits, weak partner deals, compliance duplication, low-trust acquisition, product rework and misleading reporting.
The strategic correction is straightforward: centralise what genuinely benefits from scale and localise what determines commercial performance.
Africa can remain the portfolio. The market must remain the operating unit.
That is how a regional ambition becomes a set of investable, measurable businesses rather than one optimistic total.